Bank Cash Transaction Reporting Limit Raised From Rs2 Million to Rs3 Million
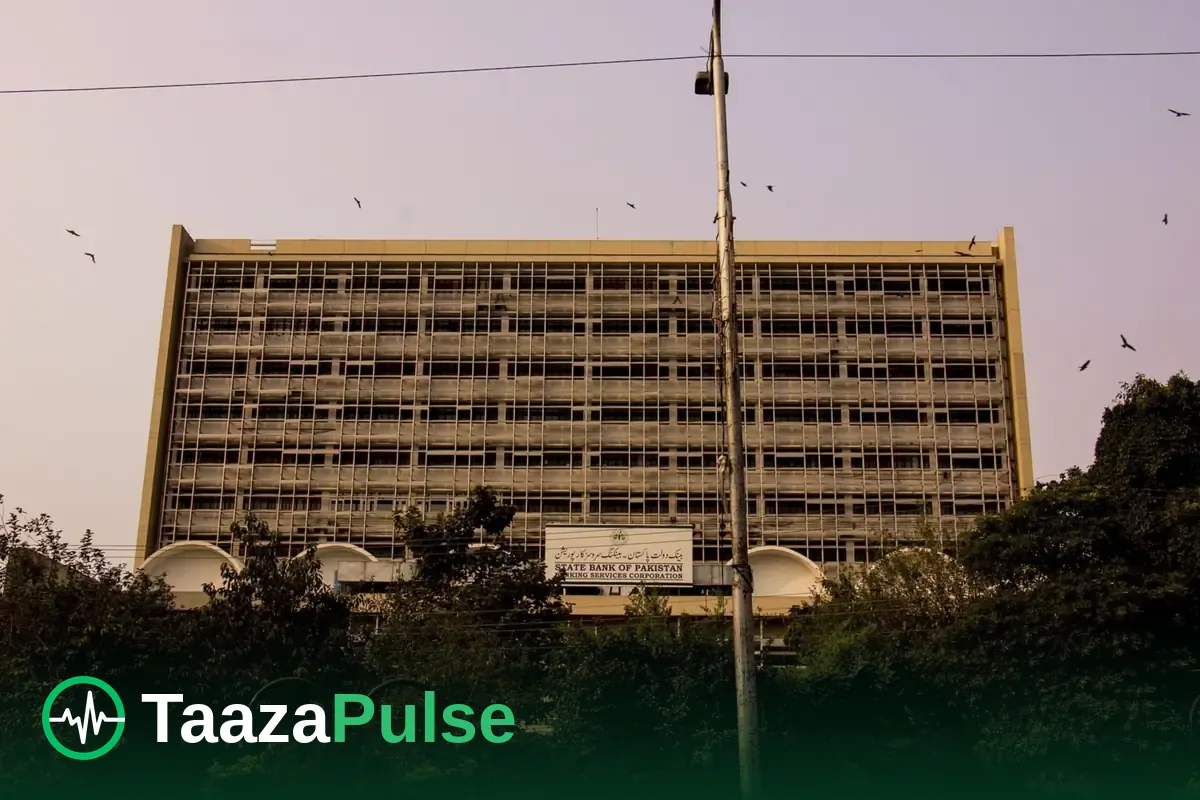
Pakistan has raised the cash-transaction reporting threshold for banks from Rs2 million to Rs3 million — a 50 per cent increase in the size of a cash deposit or withdrawal at which a bank must automatically file a Currency Transaction Report (CTR) with the Financial Monitoring Unit (FMU). The decision was taken on Tuesday by the National Executive Committee (NEC) on anti-money laundering and countering the financing of terrorism, at its 19th meeting in Islamabad, chaired by Finance Minister Muhammad Aurangzeb, Dawn reported.
The NEC approved the revision of the CTR threshold under the Anti-Money Laundering Act (AMLA) framework, as part of a wider set of decisions that also brought the new virtual-assets regulator into the AMLA schedules, added maritime piracy as a predicate offence, and reviewed the FMU's performance and its plan to use artificial intelligence and machine learning in financial-crime analysis. The cash economy is a daily reality for millions of Pakistanis, so here is what the change is, what it is not, and what it means in practice — with one important caveat about timing, set out below.
What exactly has changed
The threshold that triggers an automatic cash report moves from Rs2 million to Rs3 million. The reporting line has stood at Rs2 million since 2015, when the State Bank directed banks to file CTRs for cash transactions at or above that figure. A CTR is a routine regulatory report — not an accusation, not a tax notice and not a freeze. When a customer's cash transaction reaches the threshold, the bank sends the details to the FMU, the State Bank-based unit that receives and analyses financial-intelligence reports and passes disseminations to investigation agencies where analysis warrants it.
The NEC is the apex body of Pakistan's AML/CFT system: the committee that sets the national framework within which the FMU, the State Bank and the reporting institutions operate. The finance minister told the meeting's participants that the FMU needed a clear roadmap, with timelines, for the coming period — and the committee reviewed the unit's plan to strengthen its analysis with AI and machine-learning tools, a sign that the system intends to rely more on smarter analysis of reports and less on sheer volume of them.
CTR versus STR: the distinction that matters
Two kinds of report flow from banks to the FMU, and confusing them produces most of the anxiety around thresholds. A Currency Transaction Report is automatic and size-based: cash reaches the line, a report is filed, no suspicion is implied, and millions of entirely legitimate transactions — a trader depositing a day's takings, a family withdrawing for a wedding or a property token — are reported this way every year.
A Suspicious Transaction Report (STR) is different: it is judgment-based and has no minimum size. If a transaction looks wrong — inconsistent with what the bank knows of the customer, structured oddly, or unexplained — the bank must report it whether it is Rs50,000 or Rs50 million. Raising the CTR line to Rs3 million therefore does not create a "safe zone" below it: suspicion reporting continues at every level. The FMU's own public guidance makes the related warning explicit — breaking a large cash transaction into smaller pieces so that each piece falls under the reporting line, a practice known as structuring or smurfing, is itself treated as a red flag that banks are trained to spot and report. Anyone tempted to split a Rs3 million deposit into two Rs1.5 million ones to "avoid the report" would be doing the one thing most likely to generate the other kind of report.
What it means for account holders and businesses
For ordinary account holders, the practical change is narrow: cash transactions between Rs2 million and Rs3 million will no longer be swept automatically into a CTR. Nothing about the change alters income-tax obligations, withholding on cash withdrawals, bank charges, or the documentation a bank may ask for under its know-your-customer rules — a bank can ask where cash came from at any amount, and routinely does. For cash-heavy businesses — wholesale and retail traders, commodity dealers, jewellers, car dealers and the many firms that settle through cash in the bazaar economy — the higher line reduces the routine-report footprint of ordinary large deposits, but the STR system and the banks' own monitoring continue unchanged.
The most important practical point is the timing caveat. The official statement of the meeting, issued through the Press Information Department, confirms that revised CTR thresholds were approved but does not itself print the Rs3 million figure or an effective date; the figure comes from Dawn's and the Express Tribune's reporting of the NEC decisions. Threshold changes of this kind take formal effect through notification in the Gazette of Pakistan, and the reporting does not state when the new line becomes operative in bank systems. Until the notification appears and banks confirm the switch, customers should assume the existing Rs2 million practice may still be applied — and no one should plan a cash transaction around the new threshold on the strength of a headline. Our explainer on how the dollar rate is set covers the other side of the same regulatory system.
The rest of the NEC package
The threshold revision was one item in a broader AML package. The committee approved including the Pakistan Virtual Assets Regulatory Authority (PVARA) — the body created to license and supervise crypto and virtual-asset businesses — in the Fourth Schedule of the AMLA as a supervisory authority for anti-money-laundering purposes, pulling the virtual-asset sector formally inside the reporting and supervision net. It approved including the maritime-piracy offence under Section 28 of the Pakistan Maritime Zones Act, 2023 in the First Schedule of the AMLA as a predicate offence — the list of crimes whose proceeds count as money laundering. And, according to the Express Tribune's account, it decided in principle to extend certain AMLA enforcement powers to provincial anti-corruption establishments, conditional on standard operating procedures being settled first.
Taken together, the package points in one direction: fewer routine reports at the margin, more analytical machinery behind them, and a wider formal perimeter — virtual assets, maritime crime, provincial enforcement — around the system. Whether the higher threshold changes behaviour on the ground will depend on the Gazette notification and on how quickly bank compliance systems are re-set; TaazaPulse will report the notification when it is issued. For the prices and rates this system ultimately protects, see our daily coverage in the economy section, including today's fuel-price revision.
Sources: Dawn — "Ceiling for reporting suspicious bank transactions raised to Rs3m" (28 October 2026); Express Tribune reporting of the NEC meeting; the Finance Ministry statement carried by the Press Information Department; State Bank/FMU public guidance on currency and suspicious transaction reports.
Sources
This report is based on reporting, official statements and documents from:
- Dawn
- Express Tribune
- Press Information Department statement
- State Bank / FMU public guidance
Frequently Asked Questions
What is the new cash transaction reporting threshold in Pakistan?
Rs3 million, up from Rs2 million - a 50 per cent increase approved by the National Executive Committee (NEC) on anti-money laundering and countering the financing of terrorism at its 19th meeting on 27 October 2026, chaired by Finance Minister Muhammad Aurangzeb, as reported by Dawn.
What is a Currency Transaction Report (CTR)?
A CTR is a routine report a bank must file with the Financial Monitoring Unit (FMU) when a customer's cash transaction reaches or exceeds the set threshold. It is an automatic, size-based report - not an accusation, a tax notice or a freeze - and millions of legitimate cash transactions are reported this way.
When does the Rs3 million threshold take effect?
The NEC approved the revision on 27 October 2026, but the official Finance Ministry statement does not print an effective date, and changes of this kind take formal effect through notification in the Gazette of Pakistan. Dawn's report does not state a start date, so until the notification appears and banks confirm the switch, the existing Rs2 million practice may still be applied.
What is the difference between a CTR and an STR?
A CTR is automatic and purely size-based: cash reaches the line, a report is filed. A Suspicious Transaction Report (STR) is judgment-based and has no minimum size: if a transaction looks inconsistent or unexplained, the bank must report it at any amount. Splitting cash into smaller pieces to stay under the CTR line - structuring - is itself treated as a red flag that can trigger an STR.
Who decided to raise the threshold, and under what framework?
The National Executive Committee (NEC) on AML/CFT - the apex body of Pakistan's anti-money-laundering framework - approved the revision of CTR thresholds under the Anti-Money Laundering Act framework to make the analysis of CTRs and STRs more effective. The threshold had stood at Rs2 million since a State Bank circular of 2015.
What else did the NEC meeting decide?
The committee approved including the Pakistan Virtual Assets Regulatory Authority (PVARA) in the Fourth Schedule of the AMLA as an AML supervisor, and the maritime-piracy offence under Section 28 of the Pakistan Maritime Zones Act 2023 in the First Schedule as a predicate offence. It reviewed the FMU's performance and its plan to use AI and machine learning in analysis, and, per the Express Tribune, decided in principle to extend certain AML powers to provincial anti-corruption bodies once standard operating procedures are settled.